Overhyped? Yes. Delivering? Absolutely!
You might have heard of Travis Kelce’s fiancé. Some pop star by the name of Taylor Swift.
From what I hear she’s a pretty big deal. The 35-year-old traveled the globe with her musical entourage in 2023-24, grossing a little more than $2 billion during her Eras Tour. No other act in history ever exceeded $1 billion. There aren’t many celebrities, whether rock icons, famous athletes, or movie stars who can deliver the goods on a consistent basis. No matter the hype, these super superstars find a way to overdeliver even elevated expectations. I’d say Taylor Swift qualifies for entry into that special group.
You want to know who else does? Or in this case, what else does? Artificial Intelligence (AI) stocks that continue to beat even the most overhyped expectations. That’s exactly what happened this week as the likes of Microsoft, Apple, Meta, Alphabet, and Amazon wowed the crowds of Wall Street once again. All the Big Boy names reported quarterly earnings this week (with the exception of Nvidia which reports November 19 ), and each one delivered in Switft-esque fashion. Or if you’re more into sports, in Ohtani-esque fashion.
(Before we go any further, the stocks mentioned in this week’s commentary are for illustrative purposes only, pointing out the oversized impact that AI stocks are having on the broader market. I offer no buy-sell-hold recommendations.)
More than a few analysts believe that the hype surrounding these AI-related stocks might not be enough, that somehow the market is undervaluing them. I know, I know. Sounds a bit crazy, right? Even irresponsible. But is it? Let’s review.
Looking at your top 6 tech names (leaving out Tesla from the Mag-7), here are the price-to-earnings (P/E) levels based on forward estimated 2026 earnings.
Stock Forward P/E ratio
Nvidia 35.2
Apple 34.7
Microsoft 33.7
Amazon 31.9
Alphabet 27.9
Meta 23.3
On the higher side for sure. The S&P 500 itself currently trades at about 24x next year’s estimated earnings. But high-flying growth stocks always trade at sizeable premiums to the broader market. And remember that these companies have been consistently beating estimates. So perhaps the forward P/E ratios should actually be lower based on the likelihood that earnings estimates will be surpassed once again.
You want to see crazy? Take a gander at the forward P/E levels at the peak of the Internet bubble a quarter century ago.
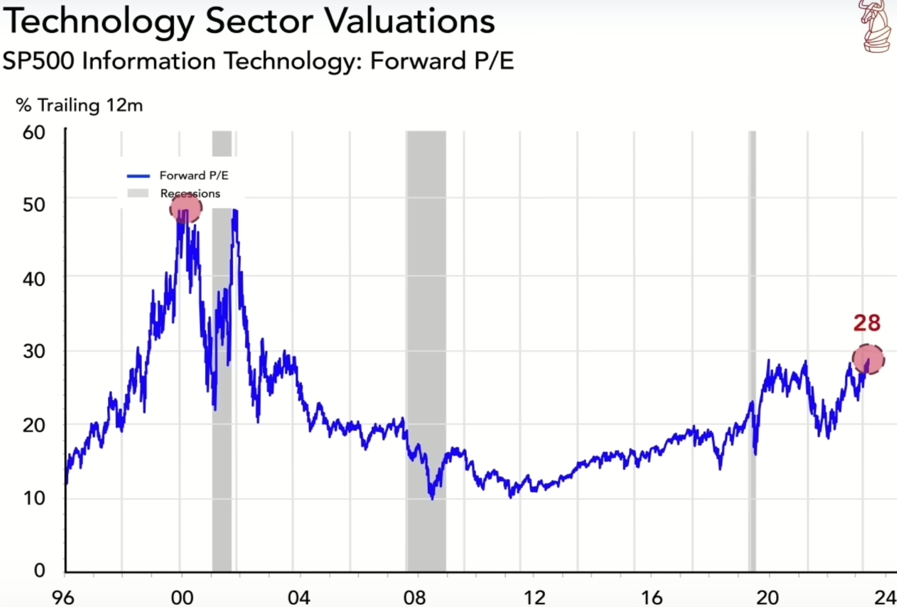
Source: Thoughts From the Frontline
This is through 2024. I looked it as of yesterday (Thursday) and the updated forward P/E ratio for the tech sector sits at 32.3. Historically on the high side to be sure. But still nowhere close to peak levels in 1999-2001.
Speaking of that bygone era, I went back to find the peak P/E levels of a few of the high-profile names during those crazy Internet days.
Stock Peak P/E ratio
Microsoft 73.4
Intel 165.5
Cisco 206.0
Qualcomm 693.9
Amazon, one of the other big names from back then, didn’t even have a P/E at the time because they had no “E” yet, not a penny of net “earnings.” Outside of a few manic areas of the market today (quantum computing stocks, anyone?), the behemoths that I mentioned earlier not only make billions of dollars every quarter, they’re also telling analysts to raise earnings expectations for 2026. And if you think they’re about to slow down their spending on AI projects next year, think again. And again. And again.
Here are selected headlines post-earnings.
“Meta forecasts ‘notably larger’ capital expenses next year thanks to investments in artificial intelligence, including aggressively building data centers to power its AI push.”
“Alphabet hikes capex again after earnings beat on strong ad, cloud demand.”“Microsoft’s infrastructure spending to meet growing cloud services demand is outpacing Wall Street expectations.”
(It should be noted that despite stronger than expected earnings, the stocks of both Meta and Microsoft were initially hit due to concerns over the need to spend so much money on their AI blueprint. Meta also had to take a nearly $16 billion one-time tax charge that it does not expect to see repeated in future quarters.)
Please don’t mistake my fact-finding mission and subsequent commentary as a current endorsement for these high-flying stocks. I offer no opinion one way or the other. (Well, I have a professional opinion and that’s reflected in the holdings we have. But I have to stay silent when it comes to public proclomations.) The market is overvalued, and that includes some of the big tech names I’m mentioning here. In fact, I’ll go so far as to say we are in the early stages of a bubble.
Yes, Forrest, I used the B-word. BUBBLE! But bubbles are very elastic and can last a lot longer than any reasonable analysis might suggest. Let’s just hope we don’t get there. We can avoid future calamity if Mr. Market will simply do his job and start taking a little off the top.
A portfolio that is occasionally trimmed, which is something we’ve been doing in small increments, will always look and perform better in the long run than an unkempt shaggy one.
Odds and Ends
- “What do you do if you’re driving in a fog? You slow down.”
So said Fed Chairman Jay Powell on Wednesday, explaining why the Fed may not cut short-term interest rates again in December.
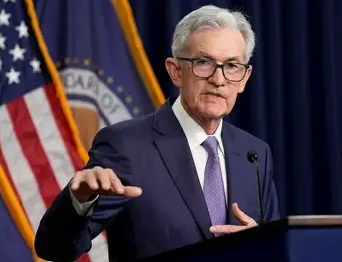
This came as news to Wall Street, which quickly turned a profitable day into a losing one for stocks. The sell-off, albeit orderly and reasonable, continued Thursday. Powell cited a lack of data available to the Fed because of the government shutdown, as well as the uncertainty over President Trump’s on-again/off-again method of tariff negotiations. To be clear, this was not just one man’s opinion, speaking of Powell. This was the result of an internal debate between voting members of the FOMC, a few hinting at the possibility of pausing future rate cuts. My best guess is that Powell and Company will still cut another 0.25% in December, but I’m hardly confident of that based on the cold feet rhetoric emanating from the Fed this week.
Long-time readers of this commentary know that for years I shrugged off concerns that our growing national debt would crimp our economy in any meaningful way. “It’ll matter when it matters,” I was fond of saying. And that was the correct assessment. But that changed earlier this year, as you know. I said that “it’s now about to matter.” I referred to some of the highest bond yields we’ve seen in nearly 20 years, causing interest payments to skyrocket on our debt payments. This picture tells the story.
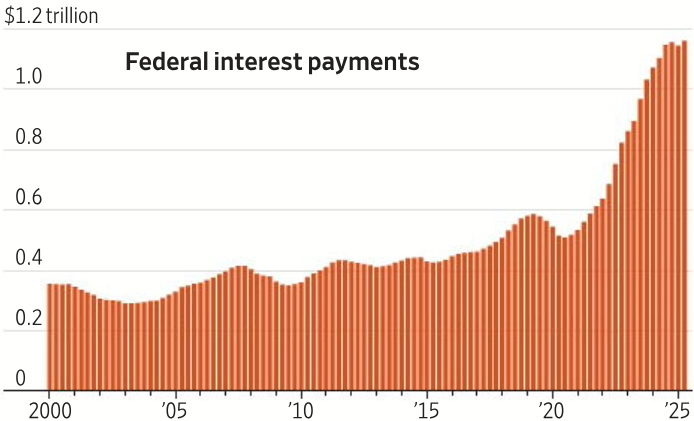
Source: Wall Street Journal, 10-25-25
Former Treasury Secretary Janet Yellen punted on a golden opportunity to lock in historically low interest rates as maturing bonds were rolling over. In her first year on the job in 2021, she could’ve locked in anywhere from 1.28% – 1.80% on 10-year bonds. Or she could’ve really been forward thinking by securing 30-year debt at between 1.80% – 2.38%. But for some inexplicable reason Yellen decided to keep rolling over maturing bonds into short-term bills and notes. In my opinion, it will now take a dramatic fall in interest rates for us to gain any reprieve from a potential debt crisis in a few years. The Fed apparently lacks the will to do so in the current environment, as I noted in the previous point. I hate to say it but we may need a fairly deep contraction (yes, I mean recession) to force the Fed’s hand and save us from ourselves. Or more accurately, save us from Congress’ irresponsible stewardship of our tax dollars.
By the time many of you read this commentary you probably engaged in some sort of Halloween-related activity. Perhaps you carved a pumpkin and placed it on your front porch. Or maybe you walked the neighborhood with your costumed kids or grandkids. Or truth be told, perhaps you shut off all your lights and headed to the basement to hide out for a few hours. That’ll be our little secret.
Here’s what a recent survey revealed in terms of our Halloween participation, or lack thereof. To no one’s surprise it really does matter if you have little rugrats scampering about your home.
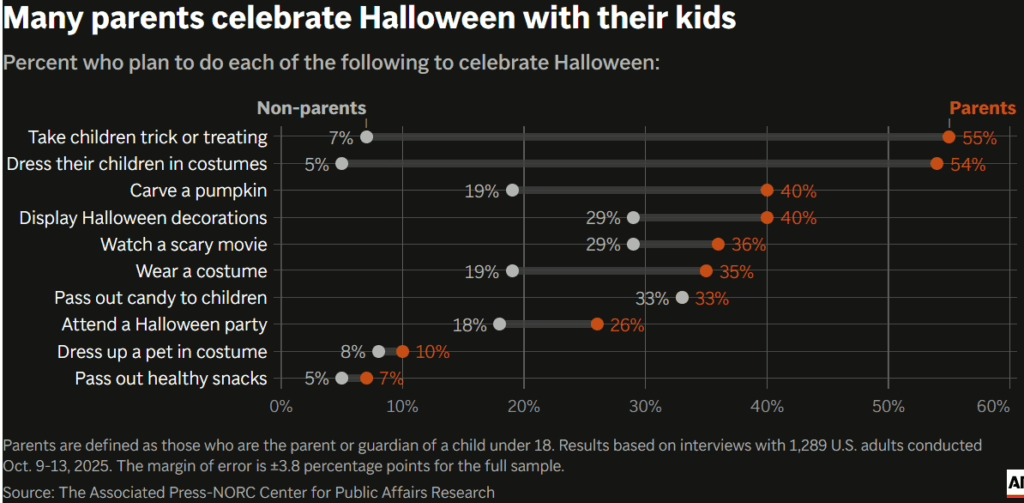
I can check the box on every one of those items from back in the day. Well, except the last entry. I never transferred my healthy eating habits to Halloween night. I mean c’mon, gimme a break. It’s Halloween for crying out loud! Candy, chocolate, those weird little things called candy corn. I love them all! Still do. I have a sweet tooth the size of Greenland. To this day my kids probably wonder how their bags of candy were 40% lighter when they woke up the next morning.
On second thought, they know. They absolutely know. After all, I still buy bags of candy every year in excitable anticipation of Halloween. And when the big night rolls around, I turn off all the lights and head downstairs to hide out for a few hours. 😊
Well look who it is!
My long-time partner, Tom Cordes, makes a rare appearance on the Simons Says podcast. My friends, you will DEFINITELY want to check this out. Here’s the link:
5 Investing Mistakes to Avoid in 2025 | Knowledgeable Strategies for Wealth & Market Planning
After viewing it, you will most certainly agree with me that Tom needs to make more frequent appearances. Don’t hesitate to email him and tell him the same thing. Just don’t tell him I put you up to it.
Happy Halloween, and have a wonderful November weekend!
Dave
The material included in this post is for informational purposes only and is not intended as an offer to buy or sell any securities. This commentary is not intended to provide tax, legal or investment advice. Any views presented in this commentary are solely those of the author and do not necessarily represent those of &Partners, LLC. While the information contained in this commentary is believed to be reliable, no representation or warranty, whether expressed or implied, is made by &Partners, LLC, and no liability or responsibility is accepted by &Partners, LLC or its affiliates as to its accuracy. Nothing contained herein is, or shall be, relied upon as a promise or representation whether as to past, present, or future performance. Past performance is not indicative of future returns.
Securities and investment advisory services offered through &Partners, LLC, a broker-dealer and investment adviser registered with the U.S. Securities and Exchange Commission and member FINRA, SIPC.